Eight years of the unglamorous part, and the rulebook finally arrived.
Stobox has been structuring real-world assets since 2018, through the years when nobody was buying. The regulation that makes this a market landed in 2026, and the work that takes eight years to do is already done.
- ✓Private company: you can lose the entire amount
- ✓The documents govern
- ✓Not investment advice
The market just became legal, and we are already in the room.
Three things had to be true at once. They are, and the order they happened in is the whole argument.
Tokenized securities went from a question counsel could not answer to a procedure with a filing.
That is the change that turns an experiment into a market.
The largest asset managers in the world tokenized funds before the rules were settled.
The demand side did not wait, which is unusual and worth noticing.
Stobox is a backer of ERC-7943, the permissioned token standard the market converged on, and issues on it.
Being early to a standard is only useful if you are still there when it wins.
Not a thesis. A live track record.
$305M+ in assets structured and supported for 100+ clients across 20+ jurisdictions since 2018, through a full lifecycle rather than to a signature. FY2024 was GAAP-profitable.
The record, the raise and the token.
A client who buys one usually needs the next, which is why the revenue per client compounds without new acquisition.
Published flat fees at every layer.
We are not paid more because a client raises more, which removes the incentive that makes most of this industry untrustworthy.
The specialists do the part that needs judgement.
The software does the part that does not, and that part is most of it.
Three products, in the order the work happens.
A company that is not organized cannot raise, and a raise that is not prepared cannot be tokenized into anything a counterparty accepts. Most of this market sells the third job. We do all three.
The record layer
One canonical, verifiable company record, scored against what investors, lenders and auditors expect.
About Intelligence →The capital layer
An offering prepared from that record and sold through licensed broker-dealer partners. Never a percentage of your raise.
About Raisable →The on-chain layer
A compliant tokenized security with an on-chain registry. Non-custodial, software-only.
About Compass →
Being early is only useful if you are still there.
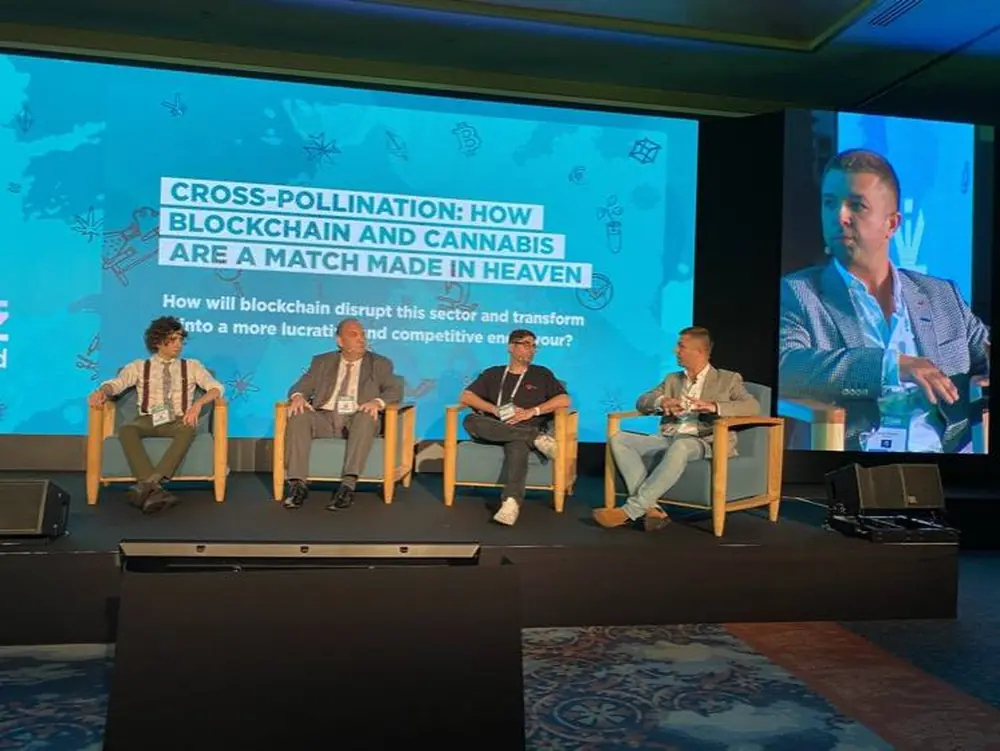
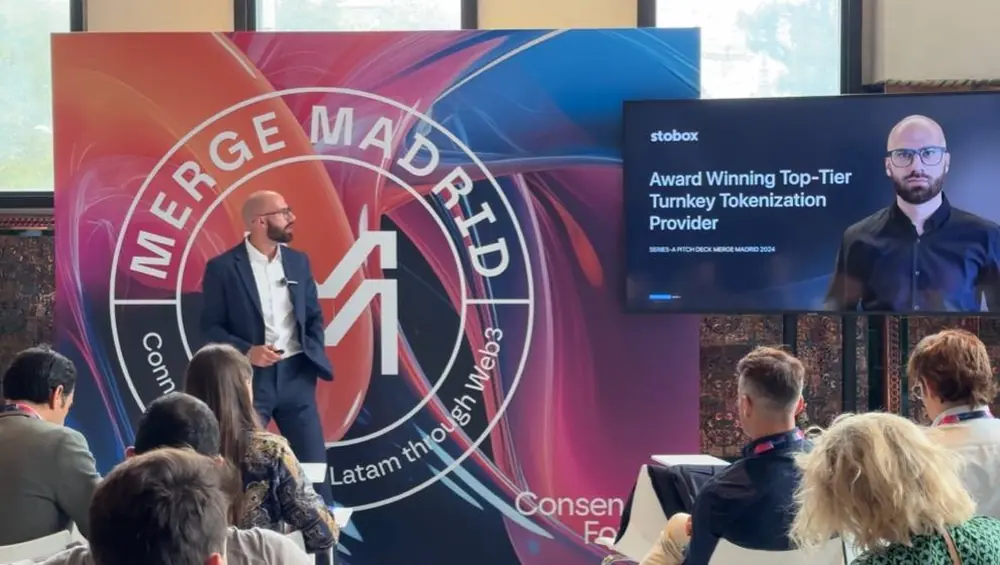
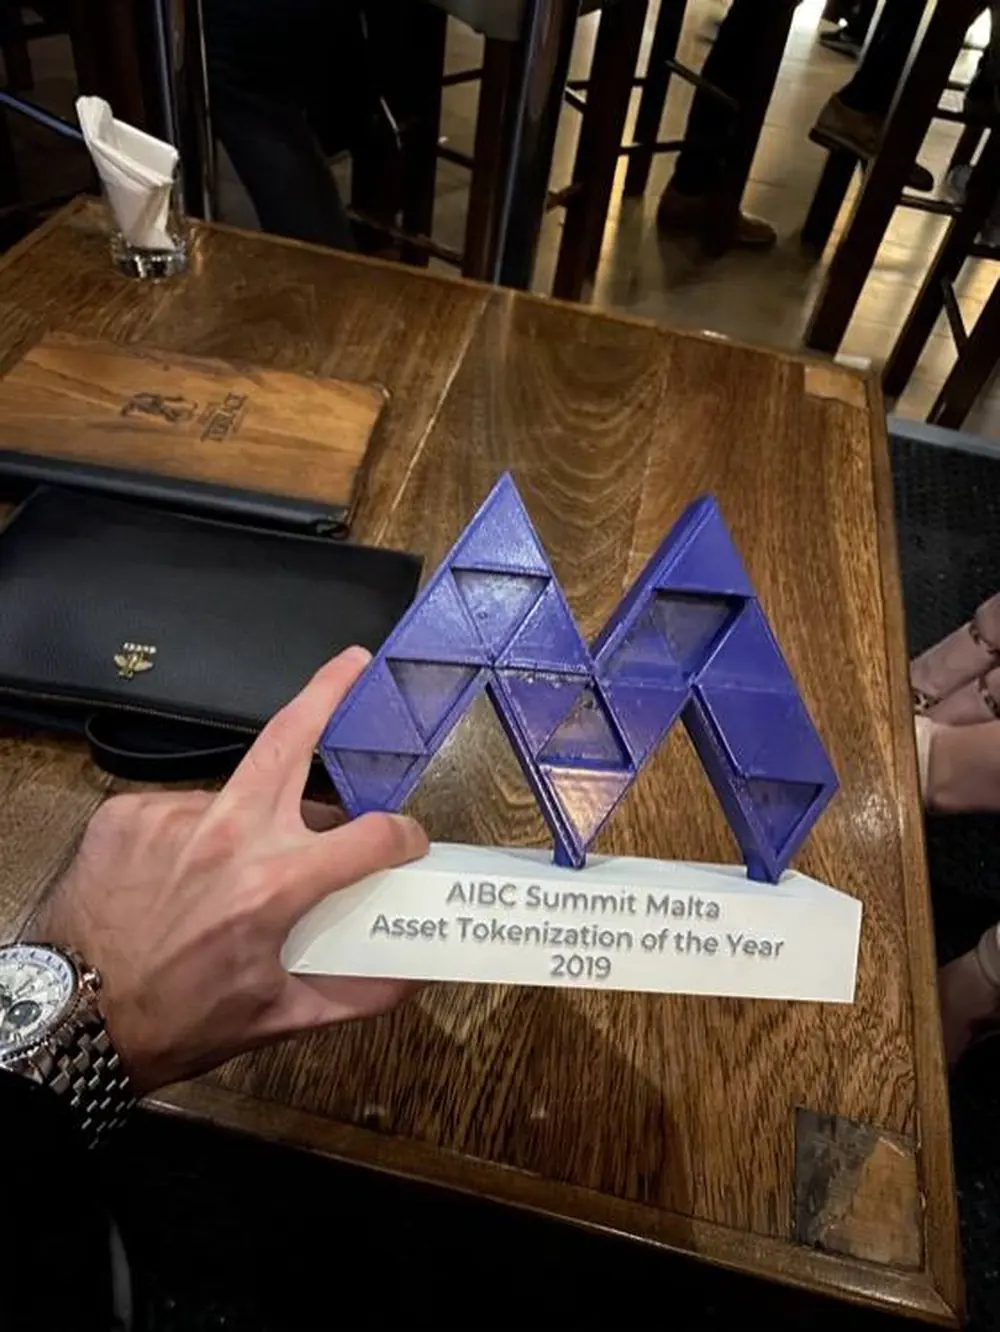
Conferences, regulators, summits and client sites since 2018. This is what the unglamorous part looks like in the years when nobody is buying.
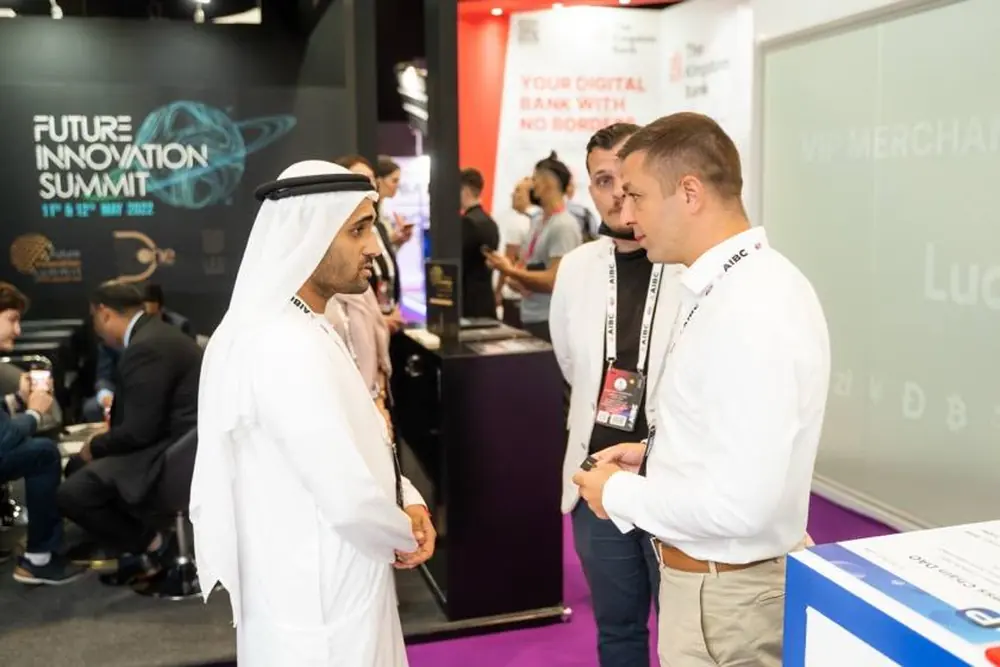
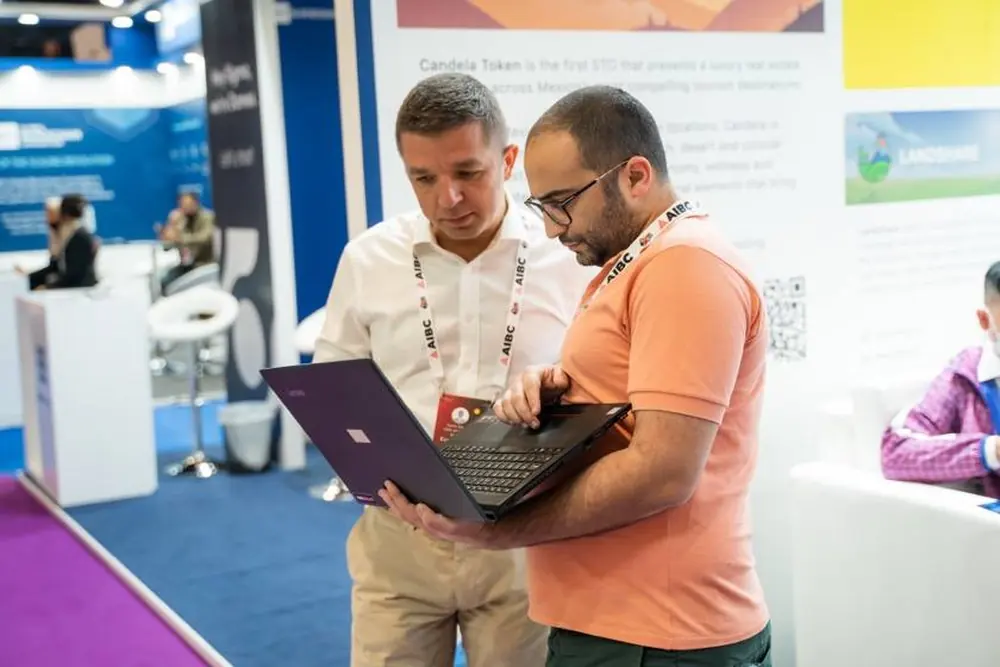
We tokenized our own equity on our own rails.
STBX runs on Stobox Compass, the same compliant stack we sell. Our cap table is on our own software, which means a defect in it is a defect in our own ownership record.
Stobox Technologies Inc. is valued by Eqvista with its Real-Time Company Valuation, a market-based estimate; the latest mark is dated 14 July 2026.
It benchmarks against real funding rounds, secondary transactions and revenue multiples of comparable private companies. It is a professional estimate, not a live quote, and it is separate from the company’s 409A. How it was arrived at.
The Reg D 506(c) offering is supported by Silicon Prairie, a FINRA-registered broker-dealer and SEC transfer agent.
It runs accreditation checks, KYC and AML, escrow and subscription documents end to end, and maintains the official share register. Stobox does none of that itself, because Stobox is not licensed to.
One million, at seventeen and a half pre-money.
The first tranche is $1,000,000. The pre-money valuation is $17.5M, set by the company and anchored to actual FY2025 revenue, which is a different number from the Eqvista estimate and should not be confused with it. Price per share, share class and minimums are in the offering documents, not on this page. Which rail applies to you is decided by where you are and how you are verified.
Reg D 506(c)
Verified US accredited investors
- A FINRA-registered broker-dealer and an SEC transfer agent are the licensed rails of record for the offering.
- Accreditation checks, KYC and AML, escrow and subscription documents run end to end through them, not through us.
- The official share register and cap table are maintained by the transfer agent, audit-ready.
- General solicitation is permitted under the exemption, which is why you can read this page at all.
Not open yet. The subscription portal is being finalised with Silicon Prairie. Nothing can be subscribed for on this rail today. Write and we email you the day it opens.
Tell us you want inSTBX, tokenized Class-C shares
Qualified non-US investors, where permitted
- Equity issued and held on-chain, with the compliance encoded into the asset rather than written beside it.
- A private placement of our own equity, offered directly by its issuer, Stobox Tokenized Equities Ltd.
- US$2.00 per token, settled on-chain, live on Arbitrum since 2025.
- Identity verified before a token can move, and transfer rules enforced by the token itself.
Open now at stbx.stobox.io, and not available to US persons. Solely through the Offering Documents on Stobox Compass.
The STBX terms
Why I would rather you read this twice.
The founder and chief executive, on what this is and what it is not.
We started this in 2018, when tokenizing a real asset was a thing you had to argue for in every single meeting. For most of those eight years the honest answer to why now was that it was not now yet, and we built the unglamorous parts anyway: the record, the exemptions, the transfer rules, the work in twenty jurisdictions that nobody puts on a slide.
The rules arrived in 2026 and the largest asset managers in the world moved before they were finished. That is the change. It is also the reason we will not tell you this is safe. It is a private company in a market that has just become legal, and both halves of that sentence carry risk.
What we will tell you is what we have: revenue from three products against one client, a valuation set by somebody who is not us, a cap table running on our own software, and no incentive to talk you into a bigger raise, because we have never taken a percentage of one.
Gene DeyevFounder and CEO, Stobox Technologies Inc.
What you are taking on.
Private companies fail, and most of them do.
Everything on this page is a reason we think this one will not, which is not the same as evidence that it will not.
FY2024 was GAAP-profitable.
We do not claim a track record of profitability, because one year is not one.
There is no promise of a market.
A path to secondary trading through licensed venues exists; listing decisions rest with the venue.
This page is a description.
The Reg D offering and the STBX private placement each run under their own documents, and where those differ from anything here, they govern.
Said plainly, and in the frame rather than in small print.
If any of this is a surprise at the end of the page, the page was written badly.
Nothing on this page is investment advice, a recommendation, or an offer to sell or a solicitation of an offer to buy any security.
It is a description of a company and of an offering that exists under its own documents.
The Reg D 506(c) offering is open to verified accredited investors only.
Accreditation is verified by a licensed broker-dealer, not self-certified, and general solicitation is permitted under that exemption, which is why this page may be read publicly.
Stobox Technologies Inc. is not a broker-dealer, not an investment adviser, not a transfer agent and not a law firm.
Regulated activity in the round is performed by licensed parties under their own registrations.
Terms that bind are in the offering documents. Where anything on this page differs from them, they govern.
Forward-looking statements describe what we intend, not what will happen. Private companies fail. You may lose the entire amount you invest. There is no promise of a market; a path to secondary trading through licensed venues exists for the tokenized route, and listing decisions rest with the venue.
The questions that decide it.
What am I buying?
Equity in Stobox Technologies Inc. Two routes exist and both give you the same underlying ownership: a Reg D 506(c) subscription through a FINRA-registered broker-dealer for verified US accredited investors, or tokenized Class-C shares as STBX for qualified non-US investors, offered directly by their issuer.
Is Stobox profitable?
FY2024 was GAAP-profitable. That is one year of GAAP accounts in a company that has been operating since 2018, and it is the honest way to say it: profitable once, not profitable throughout.
Where does the revenue come from?
Three products against one client: the record, the raise and the token. We charge published flat fees for each and never take a percentage of what a client raises, at any layer, at any point.
How is the valuation set?
Independently, not by us. The valuation page carries the method and who did it.
What happens if the market does not arrive?
You lose your money. That is the honest answer. The rulebook landing and institutions moving are reasons to believe the market is arriving, not guarantees that it will, and eight years of work does not entitle anyone to a return.
Can I sell?
Assume not. This is private equity in a private company. There is a path to secondary trading through licensed venues for the tokenized route, and the venue decides whether to list.
Updated 3 October 2026
 Talk to us
Before you decide anything.
The round is open to verified accredited investors. If you want the documents, the data room, or an hour with the people who would spend the money, ask.